Trusted Mortgage Advisors
Mortgages Simplifiedin the GTA
with an experienced mortgage broker
Expert mortgage advice that puts your goals first.
Clear guidance. Better options. Real support.
Clear Advice
You Can Understand
Fast Approvals
When You Need Them
Solutions for
Unique Situations
Support From
Start to Finish
As featured in
Canadian Mortgage Professional
CMP Top 75 Brokers 2026 (#15 in Canada)The June 4, 2026 Mortgage Professional profile records CMP Top 75 recognition for 2023, 2024, 2025, and 2026.
Mortgage Professional, June 2026
Micky Khaneka finds a wayPublished 4 June 2026. A lender decline is where a different reading of the file begins.
Nationally Recognised
Award-Winning Mortgage Expertise
Elite Hall of Fame
CMP Top 75 Broker 2026
President's Platinum Club – Top 1%
Pinnacle Club – Top 0.5%
About MKG Mortgages
Mortgage Guidance Built Around You
At MKG Mortgages, we believe the mortgage process should feel clear, strategic, and stress-free. Every client's situation is different, so we take the time to understand your goals, explain your options, and structure a solution that fits your life — not just the bank's checklist.
With over 15 years of experience in banking and mortgage advisory, MKG brings deep expertise developed inside major financial institutions - which means we understand how lenders think, what they look for, and how to position your file for the best possible outcome. That insider perspective, combined with nationally recognized advisory excellence, is what sets us apart.
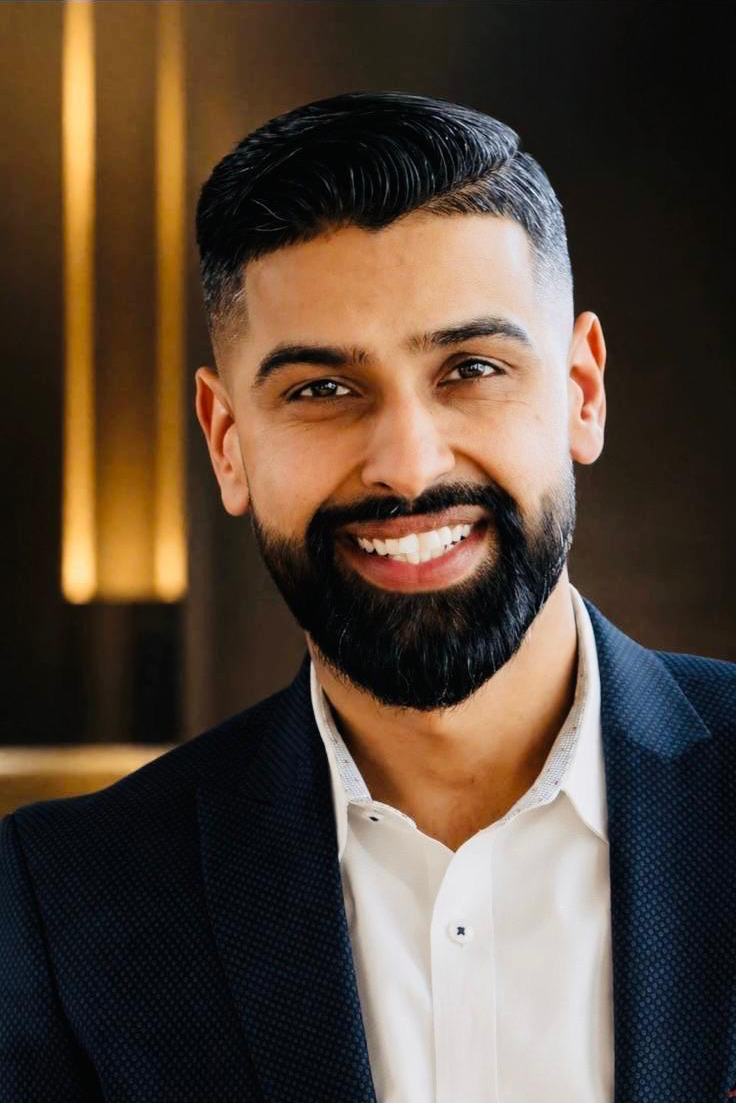
Micky Khaneka
Licensed Mortgage Broker
Our Philosophy
Why Clients Choose MKG Mortgages
We're not just processing applications — we're building mortgage strategies around real people with real goals.
- Starts with your goals and financial timeline
- Built around you, not the bank
- Custom mortgage strategy for your situation
- Renewal, refinance, and portfolio support
- Solutions for complex and non-traditional files
- 100% transparent — no surprises
Who We Help
Mortgage Solutions for Every Scenario
Whether this is your first home or an investment property, we have a strategy built for you.
Home Purchase
A home purchase mortgage finances the house or condo you are buying. The down payment, the payment, and the condition dates are set before the offer, for clients across the GTA.
Learn MoreFirst-Time Home Buyers
A first home is a purchase with the steps named in order: what you can carry, the cash to close, the offer, and the conditions. MKG Mortgages walks that sequence for buyers across the GTA.
Learn MoreMortgage Pre-Approval
A mortgage pre-approval is a budget before you write an offer. It is not a promise that a specific property will be funded. MKG Mortgages sets that budget for buyers across the GTA.
Learn MoreRefinancing
Refinancing replaces your current mortgage, often to change the payment, the amortization, or the amount borrowed. If the term is not over, the penalty is part of the math. MKG Mortgages runs that check across the GTA.
Learn MoreMortgage Renewals
A mortgage renewal is the date your term ends. The letter from the current lender is one offer. MKG Mortgages compares it before anything is signed, for homeowners across the GTA.
Learn MoreDebt Consolidation
Debt consolidation can roll higher-interest balances into the mortgage so there is one payment. It only helps when the equity, the cost, and the new payment all work. MKG Mortgages runs that test across the GTA.
Learn MoreSelf-Employed Mortgages
Self-employed mortgages are built from notices of assessment, T1 Generals, financial statements, and business bank statements. Stated-income and alternative-lender programs still verify those records. MKG Mortgages matches the documents to the program, across the GTA.
Learn MoreHELOC
A HELOC is a revolving limit secured by the home. You pay interest on what you draw, and the limit can sit beside the mortgage or replace part of it. MKG Mortgages compares that with a refinance for homeowners across the GTA.
Learn MoreReverse Mortgages
A reverse mortgage is for homeowners 55 and older who want to draw equity without a monthly principal-and-interest payment. The title stays in their name. MKG Mortgages walks through the cost and the effect on the estate, across the GTA.
Learn MoreSecond and Private Mortgages
A second mortgage sits behind the first. A private mortgage is short-term capital when a bank will not fund in time. Both carry lender fees, broker fees, a higher rate, and an exit. MKG Mortgages writes that exit down before an advance, across the GTA.
Learn MorePre-Construction
A pre-construction mortgage has to still be alive when the building is ready, which can be years after the agreement. Deposits, incentives, and the appraisal at occupancy are planned before that date. MKG Mortgages handles these files across the GTA.
Learn MoreInvestment Property
An investment-property mortgage is underwritten on the rent, the down payment, and the mortgages you already carry. A rental is not a second version of the house you live in. MKG Mortgages structures these purchases across the GTA.
Learn MoreNewcomers
Newcomers can buy in the GTA with a shorter Canadian credit history when the down payment, the job, and the documents line up with a program that accepts them. MKG Mortgages serves clients in English, Hindi, Punjabi and Bengali.
Learn MoreCommercial Mortgages
A commercial mortgage is financing secured by property used mainly for business or investment. The equity and the documents depend on the building and the lender. MKG Mortgages prepares these files across the GTA.
Learn MoreBusiness Loans
A business loan funds a business purpose, such as operations, equipment, or expansion. The term should match the use. MKG Mortgages places these requests with lenders across the GTA.
Learn MoreWhere we work
Areas we serve
MKG Mortgages advises across the GTA from the North York office. North York, Toronto, Vaughan (including Woodbridge), Mississauga, Brampton, Oakville, and Milton are the local hubs.
How It Works
A Simple Mortgage Process
Book a Consultation
Book a free consultation — no obligation, no hidden fees
Review Your Goals
We explore your financial picture, goals, and timeline together.
Compare Lending Options
We shop 100+ lenders and present your best options clearly.
Structure Your Mortgage
We build a strategy that fits your life, not just the bank's criteria.
Get Approved & Close
Move forward with confidence from approval through to closing day.
Book a free consultation — no obligation, no hidden fees
Client stories
Stories from clients
Planning Tool
Estimate Your Monthly Payment
Explore different home prices, down payments, and amortization periods with our free mortgage calculator — before your consultation.
Common Questions
Frequently Asked Questions
Do mortgage brokers charge a fee in Ontario?
The lender pays the broker on most residential mortgages, and any alternative/private-lending fees are disclosed upfront in writing.
Checked October 18, 2026. https://www.fsrao.ca/consumers/mortgage-brokering
What Information Do I Need Prior To My Consultation?
Current employment details, monthly liabilities, total savings. The more we know about your current financial situation, the better we can guide you in finding the right product.
How Long Does It Take To Get An Update On The Application?
During our initial call we will be able to provide an approximate amount you could qualify for. If choosing to proceed with the approval process, depending on the lender , it can typically take anywhere from 1 to 5 business days. Depending on the circumstances, we are able to request priority rush reviews for a faster turnaround time.
What Is Mortgage Qualification Based On?
There are several factors that determine mortgage eligibility such as income, credit, down payment and monthly liabilities. Although every application is unique , we have strong experience in the industry and our advisors are well trained to guide you through this process and make it as seamless as possible.
Just Sold My House, Can I Move My Mortgage To The Next Home?
You may be eligible for options to move over your existing mortgage to another property. Our agents will guide you through that process.
Can I qualify for a mortgage with bad credit in Ontario?
Often, yes. Lenders look at why your score dropped and what's happened since, not just the number. Depending on your history, we may go to a major bank, an alternative lender that's more flexible about past problems, or a short private mortgage while you rebuild.
A bigger down payment or equity helps a lot. We'll set out a plan to move you back to better rates, usually within one or two terms. Every option is subject to approval, and we're upfront about costs.
Checked October 18, 2026. This answer describes how a file is read. It is not an approval.
Is There Specific Locations That Can Be Financed?
We finance any properties within Canada. If you are looking to purchase property outside of Canada speak to a loan officer
What Is The Difference Between Fixed Rate And Variable Rate?
Fixed rates remain constant throughout the whole mortgage term, the interest rate and monthly payment will remain the same. Variable rate mortgage interest rates can fluctuate and the monthly payment may also change as interest rates rise or fall.
Is it better to use a mortgage broker or go to my bank?
Your bank can only offer its own products. As a licensed broker, we compare many lenders: big banks, credit unions, monoline lenders and alternative lenders. That means more choice on rate, rules, penalties and flexibility.
It matters most if you're self-employed, carry rental income, have a credit bump or want a lower-penalty mortgage. For most prime mortgages, the lender pays us, not you, and we tell you upfront if a file involves a fee. You can still compare us with your bank.
Checked October 18, 2026. https://www.fsrao.ca/consumers/mortgage-brokering
Is fixed or variable better right now?
It depends on you more than on the headlines. A fixed rate keeps your payment the same for the term, which suits a tight budget. A variable rate moves with prime.
It can save money if rates drop, but your payment or amortization can change. Its penalty is usually just three months' interest, which helps if you might sell or refinance. Think about how long you'll keep the home, how much payment change you could handle, and your penalty risk.
We'll compare both before you choose.
Checked October 18, 2026. https://www.canada.ca/en/financial-consumer-agency/services/mortgages/reduce-prepayment-penalties.html https://www.canada.ca/en/financial-consumer-agency/services/mortgages/choose-mortgage.html
Can I Prepay A Mortgage Before The End Of A Term?
Some lenders allow for pre payment options such as lump sum payment amounts to a certain amount or increased regular payments without causing any penalties. If flexible payment terms are important to you let our agents know and they will go through the best options for your scenario.
What languages we speak
MKG Mortgages serves clients in English, Hindi, Punjabi and Bengali.
Ready to Make Your Next Mortgage Move?
Book a free consultation — no obligation, no hidden fees
Get In Touch
Let's Talk Strategy
Reach out today to discuss your mortgage financing.